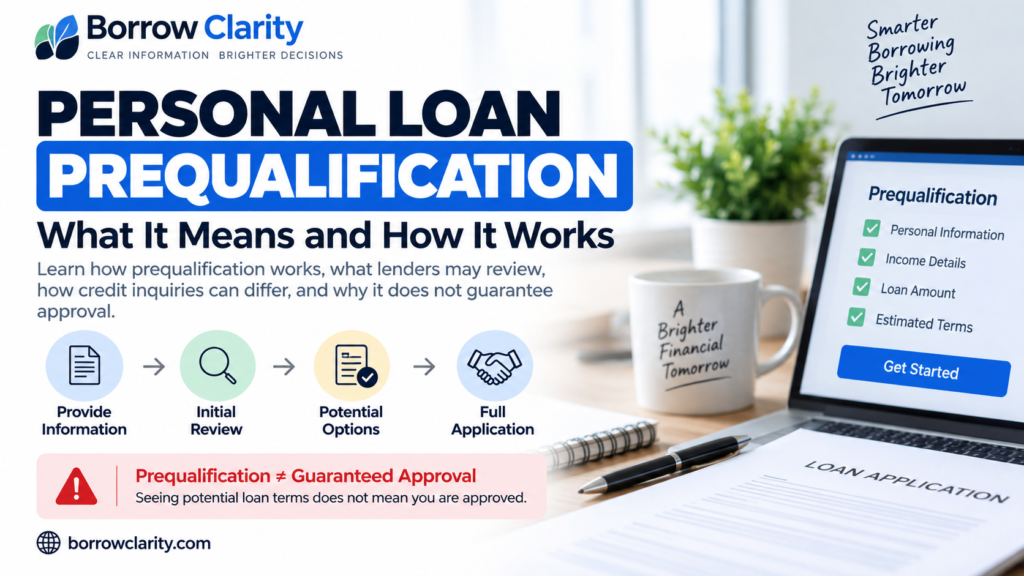
Personal loan prequalification can give you an early indication of potential loan options before completing a full application. Depending on the lender, you may provide basic financial and personal information so the lender can make a preliminary assessment.
However, prequalification is not the same as final loan approval. Processes vary by lender, and the terms you initially see may change after the lender completes additional verification and underwriting.
Quick Answer: Personal loan prequalification is generally an early screening process that may help you understand potential loan amounts, rates, or terms for which you might qualify. It is not a guaranteed loan offer or final approval. Before proceeding, check whether the lender will perform a soft or hard credit inquiry.
What Is Personal Loan Prequalification?
Prequalification generally refers to an initial evaluation performed before a lender makes a final credit decision.
You may be asked to provide information about your income, desired loan amount, housing situation, existing debts, or other financial details. The lender may use this information, and potentially information from your credit file, to determine what options may be available.
The exact process differs among lenders. Some lenders may use terms such as “prequalified,” “preapproved,” or similar language differently, so it is important to understand what a particular lender means by those terms.
Enter basic personal, income, and borrowing information requested by the lender.
The lender evaluates the information using its own screening process.
You may see estimated loan amounts, rates, or other potential terms.
If you proceed, additional information and verification may be required.
The lender completes its underwriting process and makes a final decision.
How Does Personal Loan Prequalification Work?
The process usually begins when you provide information requested by a lender or lending platform. The amount of information required can vary.
A lender may use that information to make a preliminary assessment of your potential eligibility and possible loan terms.
If you decide to continue with a full application, the lender may request additional documentation, verify the information you provided, obtain additional credit information, and perform its full underwriting process.
For more information about information lenders may consider, read Personal Loan Requirements: What You May Need to Qualify .
Does Prequalification Affect Your Credit Score?
It depends on the lender’s process.
Credit inquiries generally fall into two categories: soft inquiries and hard inquiries.
| Credit Inquiry | Typical Effect on Credit Score | Examples |
|---|---|---|
| Soft Inquiry | Does not affect your credit score | Checking your own credit report and certain prescreening activities |
| Hard Inquiry | Can affect your credit score | Often occurs when you formally apply for new credit |
The Consumer Financial Protection Bureau explains that hard inquiries commonly occur when consumers apply for new credit, while soft inquiries do not affect credit scores.
Before You Continue: Do not assume every prequalification process uses only a soft inquiry. Check the lender’s disclosures or ask whether checking potential options will result in a soft or hard credit inquiry.
Prequalification vs. Applying for a Personal Loan
Prequalification and a full loan application are not necessarily the same step.
| Prequalification | Full Application |
|---|---|
| Preliminary evaluation | Formal request for credit |
| May require less information initially | May require more complete information |
| May show potential terms | Used for the lender’s final underwriting decision |
| Does not guarantee approval | Can result in approval or denial |
| Credit inquiry process varies | Credit check commonly occurs when applying for new credit |
Does Prequalification Mean You Are Approved?
No. Being prequalified should not be treated as a guarantee of final approval.
A lender may still need to verify your income, identity, debts, credit information, or other details before making a final credit decision. Changes or differences discovered during verification can affect the lender’s decision or the terms ultimately offered.
Remember: “Prequalified” does not mean “guaranteed approval.” Review the lender’s terms and disclosures carefully before submitting a full application.
What Information May Be Requested?
The information requested during personal loan prequalification varies by lender.
Basic information used to identify you and process the request.
Information about income or other financial resources may be requested.
The amount you are considering borrowing.
Information about debts or other financial commitments may be relevant.
Some processes may ask about housing status or housing expenses.
Depending on the process, information from your credit file may be used.
These are general examples. A specific lender may request more, less, or different information.
What Should You Compare After Prequalification?
Seeing a potential loan option is only the beginning. If you receive potential terms from one or more lenders, review the cost and repayment structure rather than focusing only on whether you appear eligible.
Next step: If you receive prequalification results, compare the available information carefully before deciding whether to proceed. Review APRs, fees, repayment terms, monthly payments, and total borrowing costs in our Personal Loan Offers Comparison Guide.
Prequalification Does Not Mean You Should Borrow
Finding out that you may qualify for a loan does not necessarily mean borrowing is appropriate for your financial situation.
Before accepting any loan, consider whether the monthly payment fits your budget and whether the purpose of the loan justifies the total cost of borrowing.
A longer repayment period may reduce the required monthly payment but can also affect how much you ultimately pay over time.
See Personal Loan Repayment Terms Explained for more information.
Watch for Fake “Prequalified” Loan Offers
Not every message claiming that you are prequalified for a loan is legitimate.
Be cautious with unexpected calls, texts, emails, or online messages claiming that you have already qualified for a loan, particularly when someone pressures you to provide sensitive personal or financial information.
The Federal Trade Commission has warned about scams involving unexpected calls that tell consumers they are “prequalified” for loans they never requested.
Scam Warning: Do not treat the word “prequalified” as proof that a lender or offer is legitimate. Verify who you are dealing with before providing sensitive information.
Be Careful With Guaranteed Loan Claims
Another warning sign is a company promising guaranteed credit regardless of your credit history and requiring money upfront before providing the promised loan.
The Federal Trade Commission warns that advance-fee loan scammers may use promises of credit to convince consumers to pay processing, insurance, application, or other fees.
A legitimate application fee is not automatically a scam. The warning sign is a demand for payment tied to a promise or guarantee that you will receive the loan.
Questions to Ask Before Prequalifying
1. Will checking my options involve a soft or hard credit inquiry?
2. Is this prequalification or a formal application?
3. Are the displayed APR and other terms estimates or final terms?
4. What information will need to be verified if I continue?
5. Are there origination or other fees?
6. What repayment terms may be available?
7. Will submitting a full application result in a hard credit inquiry?
Frequently Asked Questions
What does prequalified for a personal loan mean?
It generally means a lender has performed an initial evaluation indicating that you may meet certain criteria for potential loan options. It does not guarantee final approval.
Does personal loan prequalification hurt your credit?
It depends on the lender’s process. Soft inquiries do not affect credit scores, while hard inquiries can. Check what type of inquiry the lender will use before proceeding.
Is prequalification the same as approval?
No. Final approval may require additional verification and underwriting. Potential terms shown during prequalification may also change.
Can a prequalified loan offer change?
Yes. Potential terms can change after a lender verifies information and completes its underwriting process.
Should I accept the first loan I prequalify for?
Prequalification alone does not tell you whether a loan is appropriate. Review available APRs, fees, repayment terms, monthly payments, and overall borrowing costs before making a decision.
Can a fake lender say I am prequalified?
Yes. Scammers may use loan or prequalification claims to obtain money or sensitive information. Verify the company and carefully review the offer before responding.
Bottom Line
Personal loan prequalification can be useful for understanding potential borrowing options before completing a full application, but lender processes vary.
Before proceeding, understand what information is being reviewed, whether a credit inquiry will occur, and whether that inquiry will be soft or hard. Most importantly, remember that prequalification is not a guarantee of final approval.
If you receive potential loan terms, compare the APR, fees, monthly payment, repayment period, and overall borrowing cost before deciding whether to proceed.
Continue Learning About Personal Loans
Start with our Personal Loans Guide .
Learn what lenders may review in Personal Loan Requirements .
Understand borrowing costs with Personal Loan APR Explained and Personal Loan Fees Explained .
When you’re ready to evaluate potential options, read How to Compare Personal Loan Offers .
Sources
- Consumer Financial Protection Bureau (CFPB) — When will my lender run or obtain a copy of my credit report?
- Consumer Financial Protection Bureau (CFPB) — What is a credit inquiry?
- Consumer Financial Protection Bureau (CFPB) — What’s the difference between prequalification and preapproval?
- Federal Trade Commission (FTC) — Ignore unexpected calls about loans you didn’t apply for
- Federal Trade Commission (FTC) — What to Know About Advance-Fee Loans
Disclaimer: This article is for educational and informational purposes only and should not be considered financial, legal, tax, or lending advice. Borrow Clarity is not a lender and does not make credit decisions. Prequalification processes, credit inquiry practices, eligibility requirements, APRs, fees, loan amounts, and repayment terms vary by lender and borrower. Prequalification does not guarantee approval. Always review the lender’s disclosures and consider your individual financial situation before borrowing.